
Renting vs. Selling: What Sarasota Homeowners Should Consider

Moving into a new home, relocating for work, or simply changing your investment plans can leave you with an important question: should you sell your current home or keep it as a rental property?
For Sarasota homeowners, the answer is not always as simple as comparing the monthly rent to the mortgage payment. Cash flow, equity, taxes, future repairs, local rental demand, and your own financial goals can all affect the decision.
At MRA Property Management, we work with Southwest Florida property owners who face this decision regularly. Before putting a home on the market or becoming a landlord, it helps to look at the property as an investment and understand what keeping it could actually mean financially.
Key Takeaways
- A mortgage payment that exceeds the expected rent does not automatically mean keeping the property is a bad investment.
- Rental property owners should account for operating expenses, vacancy, maintenance, and cash reserves before estimating profitability.
- Depreciation may provide tax benefits that change the financial picture of owning a rental.
- Sarasota rental demand and achievable market rent should be evaluated before deciding to keep a home.
- Selling may still be the better choice when you need access to your equity or do not want the responsibilities of rental ownership.
Start With the Property’s Real Cash Flow
One of the easiest mistakes homeowners make is looking only at rent compared with their total mortgage payment.
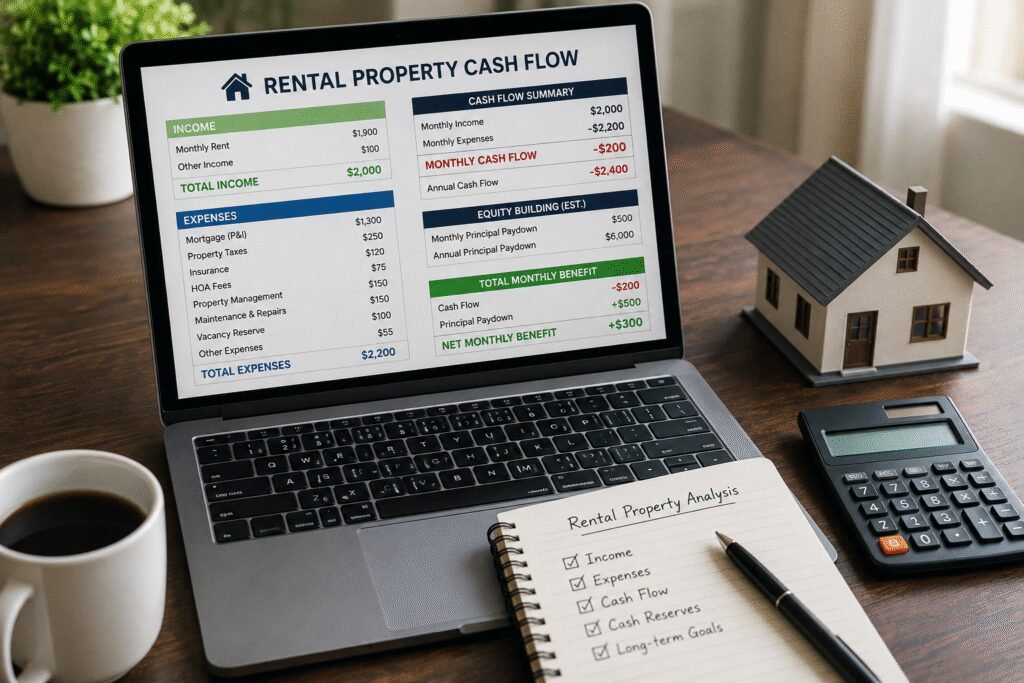

Imagine your mortgage payment is $2,300 per month and the home could rent for $1,900. At first glance, it appears that keeping the property would cost you $400 every month.
The full picture is more complicated.
Part of a mortgage payment may be reducing the principal balance on the loan, which builds equity in the property. That does not turn a negative monthly cash flow into spendable income, but it is still part of the overall financial return you receive from owning the home.
Rental property investors generally evaluate cash flow after financing and property expenses rather than relying on rent and mortgage payments alone.
Your calculation should consider expenses such as:
- Mortgage principal and interest
- Property taxes
- Insurance
- Routine maintenance
- Larger repairs and replacements
- Vacancy between tenants
- Leasing expenses
- Property management costs
- Potential HOA expenses
The goal is to understand what the property realistically costs to own versus the income and equity it may generate.
Homeowners who are new to rental ownership can also review the responsibilities and support available through MRA Property Management’s owner resources before deciding how involved they want to be.
Have questions about managing your rental?
Consider the Long-Term Value, Not Just This Month
A rental property does not need to produce a huge amount of monthly income to have potential long-term value.
Owners may benefit from a combination of rental income, mortgage principal reduction, and potential appreciation. At the same time, appreciation is never guaranteed, and every property should be evaluated on its own numbers.
That makes your timeline important.
If you expect to need the equity from your current home to purchase another property, pay down debt, or fund another major goal, selling may provide flexibility that keeping the property cannot.
If you are comfortable holding the home for several years, keeping it as a rental may deserve a closer look.
Understand How Depreciation Can Affect the Numbers
Taxes are another reason the rent-versus-sell calculation can be more complicated than it first appears.
Residential rental property may qualify for depreciation, allowing an owner to recover certain costs of the property over time for tax purposes. Federal rules covering rental income, expenses, and depreciation provide more detail on how rental property taxation works.
Depreciation can potentially reduce taxable rental income, but the exact impact depends on the property and the owner’s individual tax situation.
Before making a decision based on potential tax benefits, speak with a qualified tax professional or CPA who can evaluate your specific circumstances.
Make Sure You Have Enough Cash Reserves
Owning a rental property means accepting expenses that do not always arrive on schedule.

An air conditioner can fail during a Sarasota summer. A water heater can need replacement without warning. Florida property owners may also face storm-related repairs, insurance deductibles, and other unexpected costs.
A practical starting point is having roughly three to six months of property expenses available as cash reserves.
Reserves help turn an unexpected repair into a manageable ownership expense rather than a financial emergency.
They can also help cover periods of vacancy between tenants. Rental income should never be treated as though the property will remain occupied and maintenance-free every month of every year.
Professional management can reduce the amount of day-to-day work required from an owner. Full-service rental property management can include leasing, tenant communication, maintenance coordination, rent collection, inspections, and other ongoing responsibilities.
Keeping up with maintenance is easier when you have a local team
Look at Sarasota’s Rental Market
Your home’s rental potential also depends heavily on the local market.

A property that performs well as a rental in one neighborhood may produce very different results somewhere else. Property type, location, condition, bedroom count, amenities, competition, and tenant demand can all influence achievable rent.
Reviewing current rental market and housing data can provide useful context, but broad market statistics should not replace a property-specific rental evaluation.
Before deciding to keep your Sarasota home, determine what similar properties are actually renting for and how your home compares with competing rentals.
An achievable rental estimate can completely change the rent-versus-sell calculation.
When Selling May Be the Better Choice
Keeping a home as a rental is not automatically the right financial move.
Selling may be worth serious consideration if:
- You need the equity for your next home or another investment
- The property would consistently create an uncomfortable cash shortfall
- You do not have adequate reserves for repairs and vacancies
- The home requires significant work before becoming rental-ready
- Local rental demand does not support the rent you would need
- You simply do not want the responsibilities associated with being a landlord
There is nothing wrong with choosing liquidity and simplicity over becoming a rental property owner.
The important part is making that choice after comparing the realistic financial outcomes rather than assuming that renting or selling is automatically better.
Get Real Numbers Before You Decide
Before listing the property for sale, find out what it could realistically earn as a rental.
Compare that estimate against your mortgage, operating costs, expected maintenance, reserves, and long-term goals. Then consider how much equity you would receive if you sold today.
If you want help evaluating the rental side of the equation, you can request a rental property analysis to better understand what your Sarasota property may look like as a rental.
Final Thoughts
Deciding whether to rent or sell your Sarasota home comes down to more than one number. Real cash flow, equity growth, depreciation, cash reserves, local rental demand, and your personal financial plans all deserve consideration.
MRA Property Management helps Southwest Florida homeowners understand the rental side of that decision so they can compare their options with clearer numbers. Whether you ultimately rent or sell, understanding the complete financial picture can help you make a decision that fits your goals.
Curious what professional management would cost for your rental property?